Best General Liability Insurance Companies in Rhode Island

My recommendations for the best general liability insurers are based on more than cost, though I reviewed average rates from 10 providers across 25 industries, including professional service firms and construction companies. I assessed how each insurer’s GL policy works across different types of work, and looked for upfront restrictions and easy proof-of-insurance updates. This way, you don’t waste time on an insurer that won’t cover your business or delay a new contract.

My top picks are:

  • Choose if you offer professional services: The Hartford
  • Choose if you offer high-risk, hands-on services: ERGO NEXT
  • Choose if you want to compare multiple carriers: Simply Business
  • Choose if you're in fitness, food or service: biBerk
  • Choose if you do events and seasonal work: Thimble
For our Rhode Island general liability insurance ratings, we analyzed pricing, coverage options and customer experience across 408 industries within the state. Our analysis focuses on one-to-four-person businesses, which represent a large share of Rhode Island's small business market, while weighting results to ensure broader industry and location representation across Providence County, Kent County, Washington County and rural markets across the state.

To do this, we evaluated over 20,000 business profiles, more than 300 customer experience data points and performed in-depth analysis of coverage contracts and endorsements to compare how insurers serve Rhode Island businesses consistently across different industries and regions. 

We then rated each company across categories of affordability (50%), customer experience (30%) and coverage options and terms (20%) to form an overall rating. For a detailed breakdown of the metrics, scoring methodology and pricing analysis specific to Rhode Island, see our full methodology.

95%

% of Small Businesses Covered

Over 20,000

Business Profiles Studied

324

Customer Experiences Analyzed

The Hartford

The Hartford: Best Overall, Best for Professional and Office-Based Industries

On The Hartford's site
COMPANY HIGHLIGHTS

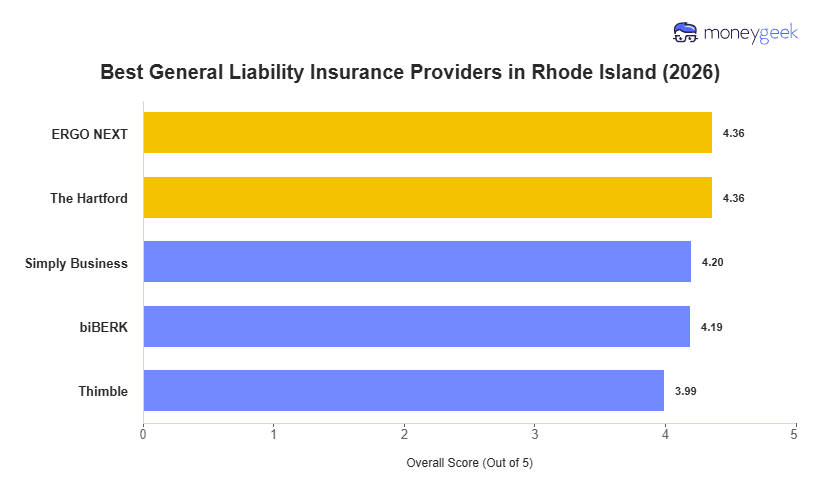
The Hartford is the best and cheapest general liability insurer in Rhode Island, ranking first overall in our study with the top scores in affordability and coverage options. Across the state, it leads affordability in seven of 25 industries, especially those in education, health care and financial services, which see the most savings, ranging from 19% to 30%. The Hartford also holds the top spot for nearly every business size, from sole proprietors to teams of up to 49 employees and has the lowest rates on average for all employee bands except solo operators. This insurer offers higher core limits (up to $2 million per occurrence and $4 million aggregate) and sets its rented-premises sublimit at $1 million. Rhode Island contractors also get the General Liability Choice® broad form endorsement, which adds blanket additional insured and newly acquired organization coverage at no extra charge. EPLI, cyber insurance and waiver of subrogation are all available to add online, though sublimit adjustments require calling an agent.

Customer experience ranks lower, with a noticeable gap between post-purchase service and the buying process. Billing flexibility, endorsement processing and support responsiveness all rank at the top and claims handling ranks second, with Rhode Island business owners reporting faster-than-average resolution for liability claims from venue incidents and job site accidents. Users scored the buying process lower since certificates of insurance need to be requested rather than accessed on demand, which slows things down.

Learn More: The Hartford Review

ERGO NEXT

ERGO NEXT: Best for Hands-On and Higher-Risk Industries

On ERGO NEXT's site
COMPANY HIGHLIGHTS

ERGO NEXT ties with The Hartford for first overall in Rhode Island, though it excels in different areas. ERGO NEXT's edge is customer experience: its fully digital platform lets Rhode Island business owners get quoted, buy coverage and receive a COI in about 10 minutes. Rhode Island contractors and event vendors can add additional insureds through the app for free, and plumbers, electricians and cleaners can attach tools and equipment coverage. Users rate policy management second, with instant certificate access and 24/7 account control through the mobile app. Claims handling ranks lower, with reports of settlement disputes, slow resolution timelines and limited live support for complex claims.

It’s the second most-affordable provider in Rhode Island, providing the most savings in hands-on and higher-risk industries: hospitality (34%), manufacturing (29%) and construction (22%). ERGO NEXT is the best option for sole proprietors and micro-businesses with one to four employees. Core limits max out at $1 million per occurrence and $2 million aggregate, and endorsement options are more limited. 

Learn More: ERGO NEXT Review

Simply Business

Simply Business: Best for Comparing Multiple Carriers

On Simply Business site
COMPANY HIGHLIGHTS

Simply Business ranks third overall in our general liability study in Rhode Island, with customer experience placing second. As a broker, Simply Business connects Rhode Island business owners with multiple insurers (Hiscox, Travelers, The Hartford, Markel and others) through a single online quote process. You can compare limit structures, endorsements and pricing from several carriers in one session, and contract-related add-ons like waiver of subrogation and a primary and noncontributory clause are also available online. Customer experience got top scores, though the broker model means two different experiences. Quotes take about 10 minutes and Trustpilot reviews praise helpful reps. After purchase, policy changes and claims go through whichever carrier underwrites your policy, not Simply Business, so the post-sale experience varies.

Although it’s not as affordable as other providers, several Rhode Island industries see solid savings: repair and maintenance (26%), retail (20%) and wholesale (20%). But seven industries cost more than the Rhode Island benchmark, including construction (10% above), marketing (15% above) and nonprofits (9% above).

Learn More: Simply Business Review

biBerk

biBerk: Best for Fitness, Food and Service Businesses

COMPANY HIGHLIGHTS

biBerk is the fourth-best general liability insurer in Rhode Island, backed by Berkshire Hathaway's A++ financial rating and a positive buying process. Unlike purely digital carriers, biBerk lets you call licensed agents before purchasing, who reviewers consistently praise for their patience and knowledge. Scores for service ranks lower after the policy is in place, though: adding an additional insured can take up to two days, customer reviews report hold times of 60 minutes or more and resolution speed gets mixed feedback.

Active-service industries see the most savings from biBerk. These include fitness (21%), real estate (20%), cleaning (19%), recreation (18%) and food and beverage (16%). Its endorsement menu is relatively broad, with liquor liability, cyber, hired auto and contractor tools/equipment all available, though lower sublimits translate to a lower ranking: $100,000 for rented premises and $10,000 for MedPay. biBerk also offers a $300,000 minimum per-occurrence limit, a unique option for very low-risk Rhode Island businesses that want to keep premiums down.

Learn More: biBerk Review

Thimble

Thimble: Best for Event Vendors and Seasonal Contractors

COMPANY HIGHLIGHTS

With an on-demand coverage model, Thimble ranks fifth overall for general liability insurance. You can buy general liability policies by the hour, day, month or year, something that no other provider in our study offers, making it a good fit for Rhode Island event vendors, seasonal contractors and project-based freelancers. However, sublimits are low ($100,000 for rented premises), equipment coverage caps at $5,000 and there's no liquor liability or umbrella option. 

Thimble offers a positive buying process, with quotes in under 60 seconds and free, unlimited COIs. It has no phone support. A third-party administrator processes all claims, and Trustpilot reviewers report resolution timelines of months and settlement offers below repair costs. Thimble's rates run above the Rhode Island average for most industries. Manufacturing saves 19%, and construction saves 17%.

Learn More: Thimble Review

What Determines the Best General Liability Insurance for Rhode Island Businesses

Two businesses operating a few miles apart could need vastly different liability protection. A marine repair shop may have problems appear after a vessel leaves, while a caterer may need event venues added to its policy. Look for general liability insurance in Rhode Island that fits those day-to-day realities as well as your budget.

How to Choose the Best General Liability Insurance in Rhode Island

Rhode Island's small business market runs heavy on hospitality, marine trades, skilled contractors and professional services, and each comes with its own liability exposure. These six steps help you work through your options in a logical order so you get general liability insurance coverage that fits your business.

  1. 1

    Optimize your payment and coverage structure

    Start by getting clear on your own risk. A daycare in Cranston and a tattoo studio on Wickenden Street don't face the same exposure, and your coverage and payment choices should reflect that.

    Ask yourself:

    • Do your leases or contracts, especially in Providence's College Hill and Federal Hill districts, set their own general liability requirements?
    • Does your work bring foot traffic, waterfront access or job site visits? Each one raises the chance of a property damage or bodily injury claim.
    • Does your revenue rise and fall with summer tourism, holiday catering or wedding season? If so, would paying annually help your cash flow in slow months?
    • Would a higher deductible leave room in your budget for endorsements as you grow?

    Most small businesses in Rhode Island begin at $1 million per occurrence and $2 million aggregate, though a marine services company in Warren would probably need more. From there, decide how to structure the policy and whether a higher deductible buys you room for broader coverage.

    Read More: How Much General Liability Insurance Do You Need?

  2. 2

    Choose your primary priority

    Businesses shop for coverage from different positions, and yours should decide what you weigh most. Choose the priority that matches where you are today. When two providers look about even, that's what settles it.

    • Pricing predictability matters most if your margins are thin or your income rises and falls with the seasons. A lobster wholesaler in Point Judith or a beach concession stand that shuts down after Labor Day can't afford a renewal spike. Steady pricing keeps planning and reinvesting possible.
    • Service responsiveness matters most if you rely on your insurer to move quickly. A restoration contractor doing storm repairs across Washington County, or a caterer handling several venues in wedding season, can't wait days for documents or policy changes.
    • Coverage flexibility matters most if you're growing or your risks are shifting. A boat repair shop in Tiverton adding winterization, or an event company in Newport branching into new venue types, needs limits and endorsements that scale without a carrier switch.
  3. 3

    Shortlist two to three providers

    Limit your comparison to two or three insurers. A provider that serves IT consultants well may not fit a shellfish farm in Narragansett or a masonry crew restoring historic buildings in Newport.

    Choose carriers that match your primary priority and have experience with businesses like yours. Use our breakdown of Rhode Island general liability costs to benchmark what your industry usually pays before you compare quotes.

  4. 4

    Double-check for dealbreakers before investing more time

    Check your shortlist for dealbreakers before you dig into detailed comparisons. Cross off any provider that:

    • Classifies your work differently than you'd expect. A tour company at Sakonnet Point that also rents equipment is the classic mixed-use case.
    • Can't turn certificates around in time. Municipal projects in Providence or Warwick often want proof of coverage the same day, and a slow insurer can lose you the bid.
    • Caps its limits below what your lease or contract specifies. Subcontractors on bigger Rhode Island builds, working under general contractors, run into this a lot.
    • Can't add the endorsements you'll need this term. If a Westerly caterer starts delivering beyond its home base, it may need hired and non-owned auto coverage.

    Finding these now saves you from wasting time on a provider that was never going to work.

  5. 5

    Compare your finalists using the same three lenses

    Once you've cleared the dealbreakers, evaluate your remaining providers on pricing, service and coverage, not just your primary priority.

    • Pricing: Look beyond the initial quote. Ask about renewal rate history for your industry, how audits are handled at the end of the policy and whether rate changes are communicated in advance. Seasonal businesses in Rhode Island should watch how insurers treat revenue swings during end-of-term audits, because revenue above your estimate can trigger additional premium charges.
    • Service: Check turnaround times for certificates of insurance, how easily you can update your policy and how quickly claims are acknowledged. For fast-moving work like event staffing during WaterFire season or summer tourism along the South County coast, expect mid-term changes and same-day COIs as standard.
    • Coverage: Review per-occurrence and aggregate limits, endorsement options and whether the provider lets you adjust coverage as your operations change. A roofing contractor in Coventry taking on larger commercial jobs needs a provider that can raise limits without a new policy.
  6. 6

    Use quotes as the final confirmation step

    Your Rhode Island address doesn't capture the work you regularly do in Massachusetts or Connecticut. Include that work when you compare business insurance quotes, and request the same limits and endorsements from each finalist. Before deciding, get written confirmation that the insurer accepts every service and location listed in the quote, especially marinas and other waterfront properties.

Best Small Business General Liability Insurance in Rhode Island: Bottom Line

Choose general liability coverage in Rhode Island by looking beyond the initial premium. The Hartford, ERGO NEXT and Simply Business lead the rankings. Pick the one that fits your industry, headcount and where your business operates. Prioritize pricing predictability and service quality, and confirm the provider can add coverage as your risk profile changes.

Best General Liability Insurance For Small Business in Rhode Island Chart
insurance2 icon
LOOKING FOR THE BEST INSURERS FOR OTHER COVERAGE TYPES?

The best Rhode Island business insurance includes more than just general liability. I've put together some resources so you can see which providers we recommend for other coverages you might need.

About Angelique Palenzuela-Cruz


Angelique Palenzuela-Cruz, Business Insurance Writer, MoneyGeek

Angelique Palenzuela-Cruz is a Business Insurance Content Writer at MoneyGeek, where she specializes in general liability, workers’ compensation and professional liability insurance. Her work helps small business owners understand how these policies apply to coverage, including risks like customer injuries, employee injuries, professional mistakes, client contract terms and industry-specific coverage requirements.
She primarily covers service-based businesses where liability and employee coverage decisions are especially important, including cleaning, consulting, beauty and wellness, childcare, education, fitness, food service, pet care, repair and maintenance, and other professional services.
Before joining MoneyGeek, Angelique spent nearly 12 years at Guthrie-Jensen Consultants, one of Southeast Asia’s largest management training firms, where she advanced from Training Consultant to Managing Consultant. In that role, she worked with business clients to assess operational needs, develop training programs and present performance analyses to executive decision-makers. She also helped establish Gladwin Training Consultancy, where she served in learning solutions and client service roles.
Her background gives her practical context for writing about how businesses operate, manage client expectations, structure teams and make risk decisions. At MoneyGeek, she applies that experience to business insurance content, connecting coverage to actual business needs.

LinkedIn: linkedin.com/in/ma-angela-cruz

Email Contact: angelique.palenzuela@moneygeek.com