7 Best Term Life Insurance Companies (2026)


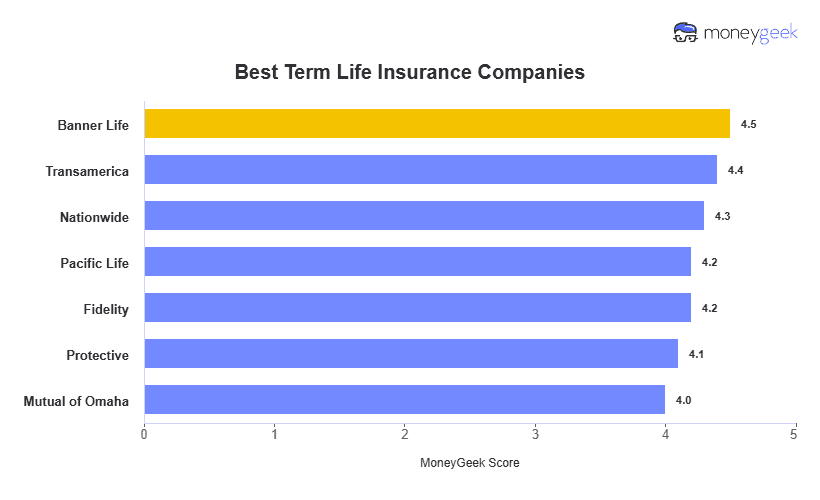
Banner Life is the best term life insurance company overall in 2026, with average monthly rates of $37 for women and $46 for men at age 40 for a 20-year, $500,000 policy. It offers up to $10 million in coverage and seven term lengths from 10 to 40 years. Transamerica matches Banner Life’s low rates and accepts applicants through age 80, while Nationwide is our top no-exam term life option.
Compare term life insurance quotes from top providers.

Select age group
Key Takeaways
blueCheck icon

Banner Life is the best overall term life company: It combines the lowest rates in our analysis with coverage up to $10 million, seven term lengths, low consumer complaints and an A+ AM Best financial strength rating.

blueCheck icon

Banner Life and Transamerica have the lowest term life rates in our analysis: Both average $37 per month for women and $46 for men at age 40 for a 20-year, $500,000 policy, but Banner Life has a much lower NAIC complaint index of 0.16 compared to Transamerica's 3.86.

blueCheck icon

No-exam limits vary widely: Banner Life allows up to $4 million without a medical exam, compared with $3 million at Pacific Life, $2 million at Transamerica and $1.5 million at Nationwide.

blueCheck icon

Seniors have fewer term life options: Maximum application ages among our recommended companies range from 55 at Nationwide to 80 at Transamerica, Pacific Life and Mutual of Omaha. Term lengths are limited to 10 years with most providers after age 65.

Best Term Life Insurance Companies

Banner Life is the best term life insurance company, with competitive monthly rates 21% to 22% below the national average, coverage up to $10 million, term lengths up to 40 years and eligibility through age 75.

Quick Picks

  • Best overall: Banner Life, with low rates, seven term lengths and up to $10 million in coverage.
  • Lowest rates: Banner Life and Transamerica, at $37 for women and $46 for men at age 40 with a 20-year, $500,000 policy.
  • No medical exam: Nationwide, with fast online applications and up to $1.5 million in coverage with or without a medical exam.
  • Coverage options: Pacific Life, with up to $10 million in coveragel, $3 million without an exam and a comprehensive rider selection.
  • Seniors: Fidelity Life, with the lowest rates in our analysis for 70-year-olds.
  • Longest terms: Banner Life or Protective, with term lengths extending to 40 years.
  • Customer experience: Mutual of Omaha, which ranked first in J.D. Power's most recent consumer satisfaction survey, A+ ratings from the BBB and an NAIC complaint index of 0.51.
Why You Can Trust Our Rankings

Overall
$37 (Female), $46 (Male)
10-40 years
20-75
4.5
Affordability
$37 (Female), $46 (Male)
10-30 years
18-80
4.4
No Exam
$45 (Female), $56 (Male)
10-30 years
21-55

4.3

Coverage Options
$38 (Female), $54 (Male)
10-30 years
18-80
4.2
Seniors
$44 (Female), $58 (Male)
10-30 years
18-70
4.2
Term Length Options
$42 (Female), $54 (Male)
10-40 years
18-75
4.1
Customer Experience
$49 (Female), $60 (Male)
10-30 years
18-80

4.0

*Rates shown are estimates of the companies MoneyGeek surveyed based on a 40-year-old with average weight and height, non-smoker, average health, 20-year term, and $500,000 coverage. Actual rates may vary by state, health profile, and insurer underwriting. Contact insurers directly for personalized quotes.

Banner Life

Banner Life

Best Overall

MoneyGeek Rating
4.5/ 5
5/5Affordability
3.7/5Customer Experience
4.5/5Coverage
  • Average Monthly Rate

    $37 (Female), $46 (Male)
  • Ages Supported

    20-75
  • Term Lengths

    10-40 years
Transamerica

Transamerica

Most Affordable

MoneyGeek Rating
4.4/ 5
4.9/5Affordability
3.7/5Customer Experience
4.4/5Coverage
  • Average Monthly Rate

    $37 (Female), $46 (Male)
  • Ages Supported

    18-80
  • Term Lengths

    10-30 years
Nationwide

Nationwide

Best No-Exam

MoneyGeek Rating
4.3/ 5
4.3/5Affordability
4.8/5Customer Experience
3.8/5Coverage
  • Average Monthly Rate

    $45 (Female), $56 (Male)
  • Ages Supported

    21-55
  • Term Lengths

    10-30 years
Pacific Life

Pacific Life

Best Coverage Options

MoneyGeek Rating
4.2/ 5
4.4/5Affordability
3.6/5Customer Experience
4.5/5Coverage Points
  • Average Monthly Rate

    $38 (Female), $54 (Male)
  • Ages Supported

    18-80
  • Term Lengths

    10-30 years
Fidelity

Fidelity

Best for Seniors

MoneyGeek Rating
4.2/ 5
4.2/5Affordability
4.2/5Customer Experience
4/5Coverage
  • Average Monthly Rate

    $44 (Female), $58 (Male)
  • Ages Supported

    18-70
  • Term Lengths

    10-30 years
Protective

Protective

Best Term Length Options

MoneyGeek Rating
4.1/ 5
4.5/5Affordability
3.5/5Customer Experience
4.2/5Coverage
  • Average Monthly Rate

    $42 (Female), $54 (Male)
  • Ages Supported

    18-75
  • Term Lengths

    10-40 years
Mutual of Omaha

Mutual of Omaha

Best Customer Experience

MoneyGeek Rating
4.0/ 5
3.8/5Affordability
4.2/5Customer Experience
4.3/5Coverage
  • Average Monthly Rate

    $49 (Female), $60 (Male)
  • Ages Supported

    18-80
  • Term Lengths

    10-30 years

How Does Term Life Insurance Work?

Term life insurance provides coverage for a set period of 10 to 40 years. You pay a fixed premium during the term, and your beneficiaries receive the death benefit if you die while the policy is active.

Shorter terms cover temporary obligations like a loan or the final years of a mortgage. Twenty- and 30-year terms are commonly used to protect income while raising children or paying off a home. A few insurers offer 35- and 40-year policies for people who want to lock in coverage for longer.

When your term ends, you can let the policy expire, renew it at higher age-based rates or convert it to a permanent policy before its deadline. Conversion rules differ by insurer, including the age limit and permanent policy types.

How Much Does Term Life Insurance Cost?

Term life insurance costs an average of $47 per month for women and $59 for men at age 40 for a 20-year, $500,000 policy. Rates increase with age. The same coverage averages $31 for women and $38 form at age 30, compared with $286 and $395 at age 60. Your health, tobacco use, coverage amount and term length also affect what you pay.

20
Female
$11
$19
$30
$41
$51
Male
$13
$22
$36
$50
$64
30
Female
$12
$20
$31
$43
$54
Male
$13
$23
$38
$53
$67
40
Female
$16
$28
$47
$67
$86
Male
$19
$35
$59
$85
$109
50
Female
$30
$59
$102
$150
$194
Male
$38
$77
$137
$201
$262
60
Female
$74
$157
$286
$421
$545
Male
$100
$215
$395
$589
$771
70
Female
$193
$431
$844
$1,171
$1,802
Male
$241
$558
$1,132
$1,577
$2,586

* Rates shown are based on quotes for nonsmokers in average health. Your actual rates vary based on health, lifestyle and other factors. Request quotes from multiple providers to find the best term life insurance for your needs.

Average Cost for Smokers vs. Nonsmokers

Smoking more than triples term life insurance rates at age 40 in our analysis. Women pay an average of $148 per month as smokers versus $47 as nonsmokers for a 20-year, $500,000 policy, while men pay $194 versus $59.

Tobacco-classification rules vary by insurer. Several companies in our ranking consider applicants for nonsmoker rates after 12 months without nicotine, while Transamerica and Nationwide require two years for the classifications shown in our review.

Female
$47
$148
218% more
Male
$59
$194
231% more

* Rates shown are for 40-year-olds in average health with a 20-year, $500,000 policy.

Estimate Your Term Life Insurance Cost

Use our free term life insurance calculator to get a personalized estimate in seconds. 

Estimates are based on average health for nonsmokers.

Select Age
Select Gender
Select Term
Select Coverage Level
Average Monthly Rate—

How to Choose the Best Term Life Insurance Policy

Key factors for selecting term life insurance:

  1. 1
    Coverage Amount

    Estimate how much money your beneficiaries would need to replace your income and cover major obligations such as a mortgage, other debts and education costs. A common starting point is roughly 10 times your annual income, but a needs-based calculation provides a more personalized estimate. Use our life insurance coverage calculator to quickly determine your coverage needs.

  2. 2
    Term Length

    Choose a term that covers your longest major financial obligation. A parent with young children or a new 30-year mortgage may need 20 to 30 years of coverage, while someone approaching retirement may need only 10 or 15 years. Longer terms cost more but keep your premium rate locked in for a longer period.

  3. 3
    Rates

    Compare life insurance quotes from multiple insurers. The lowest-priced company can change based on your age, health and coverage amount. Don't compare price alone. Financial strength, complaint history, conversion options and policy features can also affect the value of a policy you may keep for decades.

  4. 4
    Riders and Other Benefits

    Prioritize riders that solve a specific need. Accelerated death benefits give early access to part of your death benefit after a qualifying diagnosis, while waiver-of-premium riders keep coverage active during a qualifying disability. Also compare conversion privileges if you thin you'll want permanent life insurance later.

  5. 5
    Provider Financial Strength & Consumer Complaints

    Review AM Best ratings to evaluate an insurer's financial strength and NAIC complaint data to compare its complaint record with similarly sized insurers. All seven companies on our list hold AM Best ratings of A- or higher, while complaint indexes range from 0.05 at Pacific Life to 3.86 at Transamerica.

How to Get a Term Life Insurance Policy

Buying term life insurance takes 15 to 30 minutes online. Most carriers return a decision within days. No-exam policies can approve you in minutes, while fully underwritten policies that require a medical exam take two to six weeks.

  1. 1
    Gather your information before you start

    You'll need your Social Security number, driver's license, medical history, current prescriptions, height and weight, and the name and contact information of your primary care physician.

  2. 2
    Complete the application

    Answer health and lifestyle questions about your medical history, tobacco use, family health history and any high-risk hobbies like skydiving or rock climbing. Most online applications take 15 to 30 minutes.

  3. 3
    Undergo a medical exam if required

    Fully underwritten policies require a medical exam that includes blood and urine tests and takes about 30 minutes. The exam company schedules it at your home or office at no cost to you.

  4. 4
    Wait for underwriting

    No-exam policies return decisions within minutes to 48 hours. Fully underwritten policies take two to six weeks while the insurer reviews your medical records and exam results.

  5. 5
    Review your offer

    Check the coverage amount, premium, term length, beneficiary designations and any exclusions before accepting. The insurer may approve you at a higher rate than quoted if underwriting uncovers health factors.

  6. 6
    Submit your first premium payment

    Coverage starts on the effective date, which is the date your first payment is processed. Keep your confirmation documents and share your policy details with your beneficiaries.

Bottom Line

Banner Life is our best overall term life insurance company, combining some of the lowest rates in our analysis with seven term lengths, up to $10 million in coverage and a $4 million no-exam limit. Transamerica's low rates are worth comparing against Banner Life, Nationwide has a strong no-exam option and Fidelity Life has the lowest senior rates in our review. Compare quotes from multiple insurers, because the best company can change based on your age, health and coverage needs.

Best Term Life Insurance
People's top pick
1
Policygenius
  • Compare 13 top-rated carriers with one form
  • Talk to licensed agents – no commission, no pressure
  • Get rates starting at $16/month
  • Apply in under 10 minutes
On Policygenius's site

* MoneyGeek featured partner

Frequently Asked Questions

MoneyGeek's experts answered common questions about term life insurance companies and policies.

Related Articles

About Patrick Bryant


Patrick Bryant, Vertical Lead, Life & Health Insurance, MoneyGeek

Patrick Bryant is the Vertical Lead for Life and Health Insurance at MoneyGeek, where he researches insurance products, writes consumer guides and maintains the scoring methodologies behind our provider comparisons. He analyzed more than 50 life insurance carriers across multiple policy types, collecting thousands of quotes nationwide to evaluate rates, coverage options and underwriting factors. His methodologies are reviewed quarterly to reflect current market conditions and carrier data.